

Piere: Budget, Plan, Save
4.5

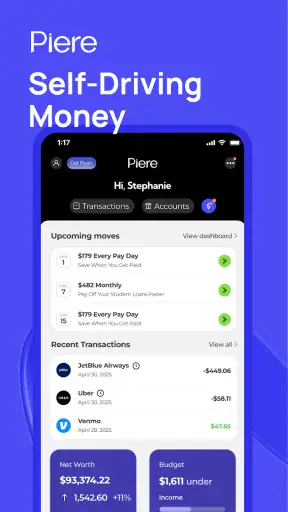
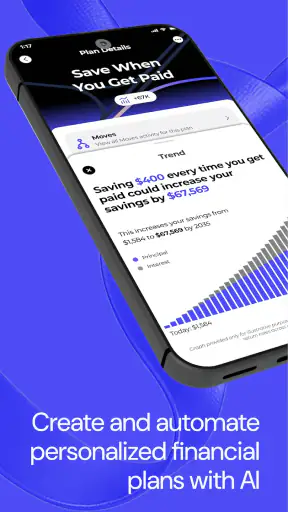
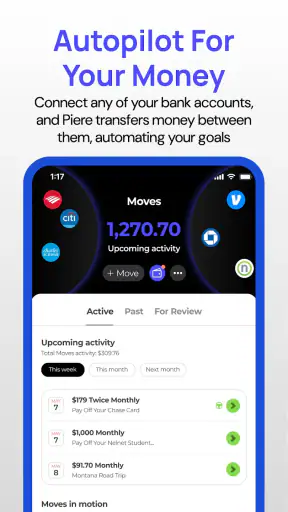
Managing money on a shared phone is rarely as simple as opening a banking app and checking a balance. One person may handle groceries, another may pay the bills, and someone else may be trying to build an emergency cushion. I tested Piere: Budget, Plan, Save with that kind of household situation in mind, and I found its central idea appealing: put everyday budgeting and saving into one place instead of relying on scattered notes, spreadsheets, and memory.
This is a finance app from UniversTech, available free of charge, with optional in-app purchases ranging from $1.99 to $79.99 per item. It is rated for Everyone, runs on operating system version 10 or later, and the current version is 6.2.2. Its store presence is already fairly established, with over 50 thousand installs, a 4.5 average from around 473 ratings, and roughly 188 written reviews. Those figures suggest a useful level of interest, but my decision to recommend it comes more from how its budgeting approach fits real household routines than from its popularity.
How Piere fits into a shared household routine
The most convincing use case is not a lone user who wants to stare at charts every evening. It is a household where money decisions are shared, but financial responsibilities are not identical. Imagine one partner buying food during the week while the other pays utilities and manages longer-term savings. Without a common view, both people can feel as if they are being careful while the household still drifts over its intended spending limit.
Piere is useful in that situation because it encourages a forward-looking routine. Instead of only asking how much is left in an account, I would use it to decide what money should do next: cover recurring needs, remain available for flexible spending, or move toward a savings goal. That distinction matters. A healthy bank balance can be misleading when several bills are still waiting to arrive.
For a shared-device household, I would make the app part of a weekly money check rather than an always-open dashboard. A short review after payday can be enough to look at planned expenses, adjust a budget, and agree on what can safely be saved. This reduces the temptation to make every small purchase a discussion while still giving both adults a common reference point.
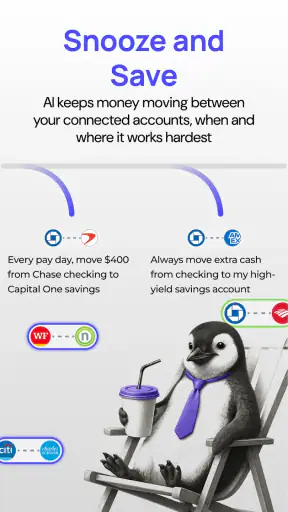
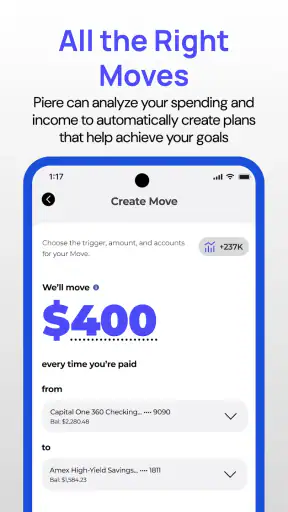
The app’s automation angle is also more practical when treated as a habit, not as magic. Automated saving works best when the household first understands which money is genuinely available. If a transfer or saving action is planned too aggressively, an upcoming annual payment can turn a good intention into a cash-flow problem. I would start with a modest target, observe one complete pay cycle, and only then make the plan more ambitious.
The important household lesson is to automate a decision you already understand, not a decision you have not checked. That is where Piere can help: it gives a place to organize the decision before making it part of the routine.
Setting boundaries before anyone shares the phone
A finance app on a shared device needs clearer boundaries than a shared shopping list. I would not treat the presence of the app as permission for every person using the phone to inspect every financial detail. Before setting it up, the adults in the household should agree on who is responsible for the account, who may review the budget, and which decisions still require a conversation.
This is especially important when a phone is passed between partners, older children, or roommates. A device can be shared while financial access remains personal. I would use the phone’s own privacy and account protections, keep the app tied to the intended user, and avoid leaving sensitive screens open. Piere may organize money, but it should not replace basic device security or a clear agreement about access.
There is also a useful difference between sharing a goal and sharing every transaction. A couple may want to work toward the same holiday fund while keeping individual discretionary spending separate. In that case, the household conversation can focus on the shared target and the planned contribution, rather than turning every personal purchase into a review. This boundary makes budgeting less intrusive and more sustainable.
Roommates need an even narrower arrangement. I would use the app to plan each person’s contribution to rent or utilities, but I would not assume that a common household goal means everyone should expose all personal finances. Piere is better suited to coordinating agreed responsibilities than to forcing complete financial transparency between people who are not partners.
Parents should also be careful with age and responsibility. The Everyone content rating makes the app broadly approachable, but that does not mean a child should manage an adult’s connected financial information. For a teenager learning to budget, I would use the ideas of categories, planned spending, and saving with money that is already under the teenager’s control. I would keep adult accounts and credentials separate.
Turning a budget into a conversation instead of a rulebook
Many budgeting tools fail in households because one person becomes the “finance manager” and everyone else receives instructions. My better approach with Piere would be to use it as a neutral starting point. The app can help show what the household intended to do, while the people involved still decide whether that plan is realistic.
A practical weekly conversation could cover three questions. What bills or necessary purchases are coming next? Which flexible category is under pressure? Is the planned saving amount still comfortable? These questions are more useful than arguing over isolated transactions, because they connect present spending with the next few days and the larger goal.
One non-obvious benefit of this method is that it exposes timing problems. A monthly budget can look fine in total while the first week contains too many commitments. I would use the planning view to notice that mismatch early, then delay a nonessential purchase or reduce the saving amount temporarily. The goal is not to make every month perfect; it is to prevent a predictable shortfall from arriving as a surprise.
Another useful workflow is to separate fixed obligations from decisions that can change. Rent, insurance, and regular service payments should not be treated like restaurant spending. If all categories are mentally equal, a household may cut the wrong things or feel unnecessarily restricted. Piere becomes more helpful when I use its budgeting structure to protect essentials first and judge flexible spending second.
For couples with different money styles, this can reduce friction. A cautious saver can see that some spending is planned rather than careless, while a spontaneous spender can see why a large purchase affects the rest of the month. The app does not solve the disagreement by itself, but it gives both people a shared framework for discussing it.
Trust, age, and the limits of shared financial visibility
I would recommend Piere more readily to adults who already trust one another and need coordination than to families looking for a supervision system. The app’s age rating is broad, but household finance is still an adult responsibility when real bank information and savings decisions are involved. Younger users can learn from a budget without being given access to the household’s complete financial picture.
Trust also changes how automation should be handled. If one person creates a saving plan on a shared device, the other person should understand what it is intended to do and when it may affect available cash. Even a well-designed plan can create stress when it is invisible to the rest of the household. I would make automated actions part of the regular money conversation and keep a small buffer outside the plan for irregular expenses.
That buffer is one of the most important practical safeguards. Budgets often account for known monthly costs but overlook school events, repairs, gifts, medical needs, or travel changes. I would not assign every available amount to a category or saving goal. Leaving breathing room makes the system less likely to be abandoned after one unusual week.
There is a privacy trade-off here. A single financial overview is convenient, but convenience can encourage over-sharing. If the household has complicated relationships, separate finances, or unresolved trust issues, a shared budgeting app may intensify tension rather than reduce it. In that case, individual budgeting tools or a simple shared total may be a better fit than one central financial workspace.
I also would not choose Piere for someone who wants a completely manual cash-envelope method. The app’s appeal is strongest when planning and saving can be organized digitally. A person who prefers writing every expense in a notebook, avoids connected financial tools, or wants absolute control over each manual entry may feel that the app’s approach adds another layer rather than removing work.
What the free entry point does and does not mean
The app is free to download and use as an entry point, which makes it easy to test without committing money immediately. That is useful for a household that wants to see whether a shared budget routine will actually last. I would spend time establishing categories and reviewing the first few weeks before considering any optional purchase.
The presence of in-app purchases means users should pay attention to which functions are included in the basic experience and which may require payment. The available purchase range extends from $1.99 to $79.99 per item, so I would not assume that every planning or automation capability belongs to the free tier. A careful user should check the purchase screen before confirming anything, especially when the app is being used on a device shared by more than one person.
This is also where household boundaries matter financially. If children or guests can access the device, purchase authentication should be protected through the device’s own settings. A free app can still create unwanted charges if purchase approval is not under the account holder’s control. I see this as a general shared-device precaution, but it is particularly relevant here because money management and optional upgrades sit side by side.
The current version, 6.2.2, gives the app a clear version identity when troubleshooting or comparing experiences across devices. Since the minimum operating system is version 10, users with older phones should check compatibility before planning a household switch. For everyone else, the sensible approach is to update through the normal app-store process and then verify that the budgeting routine still reflects the household’s actual needs.
Where it beats spreadsheets and ordinary banking apps
A spreadsheet remains excellent for people who want complete control over formulas, custom categories, and historical analysis. It can also be shared with a partner without connecting to financial accounts. However, spreadsheets depend heavily on consistent manual updates. If one person forgets to enter a purchase, the household may make decisions from an outdated picture.
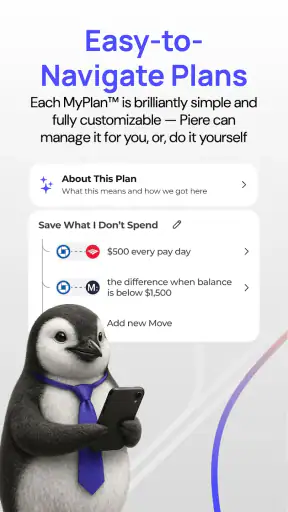
A standard banking app is faster for checking balances and transactions, but it usually reflects what has already happened. Piere’s value is in encouraging a plan for what happens next. That makes it more suitable for someone who repeatedly reaches the end of the month wondering where the money went, even though the bank app showed every transaction.
There is a trade-off. A bank app is usually the natural place to verify the final balance, while a dedicated budgeting tool asks the user to think in categories and goals. That extra structure is useful only if the household will review it. If nobody is willing to maintain a plan, the simpler banking app may be the more honest choice.
Compared with a paper budget, Piere is more convenient for changes. A paper plan can be reassuringly visible on a refrigerator, but it becomes awkward when income dates, bills, or saving priorities shift. The digital format is better for a household that needs to revise a plan without rewriting the whole system. Paper may still win for a person who finds screens distracting or wants budgeting to remain completely separate from online accounts.
The strongest distinction is therefore not that Piere replaces every alternative. It occupies the middle ground between passive account checking and highly manual financial record-keeping. I would choose it for a household that wants structure and automation but does not want to build its own spreadsheet system from scratch.
A realistic month with the app
Consider a couple paid at different times during the month. One income arrives first, covering rent and utilities, while the second arrives later and usually handles groceries, transport, and savings. At the start of the month, I would map the fixed obligations first, then decide how much of the later income can safely support the savings goal.
During the first week, an unexpectedly expensive grocery trip might make the original plan look uncomfortable. Instead of treating that as failure, I would review whether the overspend was a one-time event or a sign that the category was unrealistic. If it was temporary, the household could leave the plan intact. If it was recurring, the budget should change before the next pay cycle.
Later, when the second income arrives, the household can check the remaining obligations rather than saving a hopeful amount based only on the account balance. This is the kind of workflow where Piere’s planning emphasis earns its place. It encourages the user to connect timing, spending, and saving rather than treating each as a separate task.
For a family, I would add a simple rule: shared necessities are reviewed together, while personal spending remains within an agreed allowance. That avoids making children responsible for adult financial decisions while still teaching them that money has competing jobs. For roommates, I would narrow the process to shared bills and a contribution schedule, keeping personal budgets outside the group discussion.
Who should use it, and who should skip it
I think Piere is a good match for adults who want to move beyond checking balances, couples who need a common plan, and households that repeatedly postpone saving because the amount left over never feels clear. It is especially useful when the problem is not a lack of income tracking but a lack of coordination between upcoming obligations and longer-term goals.
I would be more cautious recommending it to someone with irregular income who needs highly specialized forecasting, unless that person is comfortable revising the plan frequently. I would also suggest another approach for users who do not want digital financial organization, who need a fully manual envelope method, or who are looking for formal parental supervision and account controls. The Everyone rating should not be mistaken for a guarantee that the app is appropriate for every age or every level of financial independence.
People who share a phone but not finances should also think carefully before combining their information. A shared goal can be enough; complete visibility may be unnecessary. Piere works best when the household agrees on the boundaries before the app becomes the center of its money routine.
After using it, my view is that the app’s real strength is behavioral. It nudges users to give money a job before spending decisions become urgent. That is more valuable than another screen full of totals, but it also means the app cannot carry the household by itself. The plan still needs honest inputs, regular attention, and agreement about who is allowed to see or change what.
For a household that wants a practical digital budget without building a complicated spreadsheet, I would recommend giving Piere a careful trial. Start with one shared goal, protect account access, leave room for irregular costs, and review the plan together before adding automation. If that routine feels helpful, the app can become a useful coordination tool. If it feels intrusive or too dependent on digital organization, a bank app, private individual budgets, or a simple spreadsheet may serve the household better.
My final verdict is positive but measured: Piere is a thoughtful finance app for planning, budgeting, and saving, particularly when two adults need to coordinate without turning every purchase into a dispute. Its free starting point lowers the barrier to testing it, while the optional purchases deserve attention before anyone spends. Used with clear boundaries and realistic expectations, it can make household money conversations calmer and more concrete.
4.5
188.00 Reviews
Pros
- Simple budgeting tools make it easy to track spending and plan ahead.
- Savings goals help turn long-term targets into manageable steps.
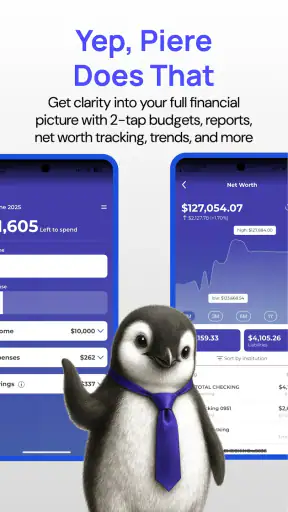
- Clear financial overviews can improve awareness of monthly habits.
- Useful reminders may help users stay consistent with planned budgets.
- Suitable for users who want a focused personal finance experience.
Cons
- Some advanced budgeting features may require a paid subscription.
- Manual transaction entry can become time-consuming for frequent purchases.
- Limited bank support may affect automatic account synchronization.
- The app may feel too basic for users needing detailed financial reports.
- Budget accuracy depends on keeping categories and transactions up to date.


